A notification from Thailand's Ministry of Finance has turned the penalty provisions of the Emergency Decree on Exchange of Information for Compliance with International Agreements on Taxation into concrete amounts: false declarations or concealed information carry a settlement fine of THB 500,000 per count, and failure to report as required carries THB 300,000 per count. The notification was posted in the Revenue Department's new-laws section on 23 September 2026, having been signed on 9 September. For Chinese-invested groups in Thailand with cross-border related-party transactions, this rule turns a "general obligation" into a "quantifiable risk".
1. What the Notification Provides
The full Thai title of the notification is ประกาศกระทรวงการคลัง เรื่อง กำหนดหลักเกณฑ์การเปรียบเทียบตามมาตรา ๓๑ แห่งพระราชกำหนดการแลกเปลี่ยนข้อมูลเพื่อปฏิบัติตามความตกลงระหว่างประเทศเกี่ยวกับภาษีอากร พ.ศ. ๒๕๖๖, which translates as "Notification of the Ministry of Finance on the Criteria for Settlement under Section 31 of the Emergency Decree on Exchange of Information for Compliance with International Agreements on Taxation, B.E. 2566". It was signed by Deputy Prime Minister and Minister of Finance เอกนิติ นิติทัณฑ์ประภาศ (Ekniti Nitithanprapas) on 9 September B.E. 2569, i.e. 9 September 2026.
The body of the notification has only two clauses, but both matter.
Clause 1 authorises the Director-General of the Revenue Department (อธิบดีกรมสรรพากร) to set "settlement fine" (ค่าปรับในการเปรียบเทียบ) standards for offences under the emergency decree, in two tiers:
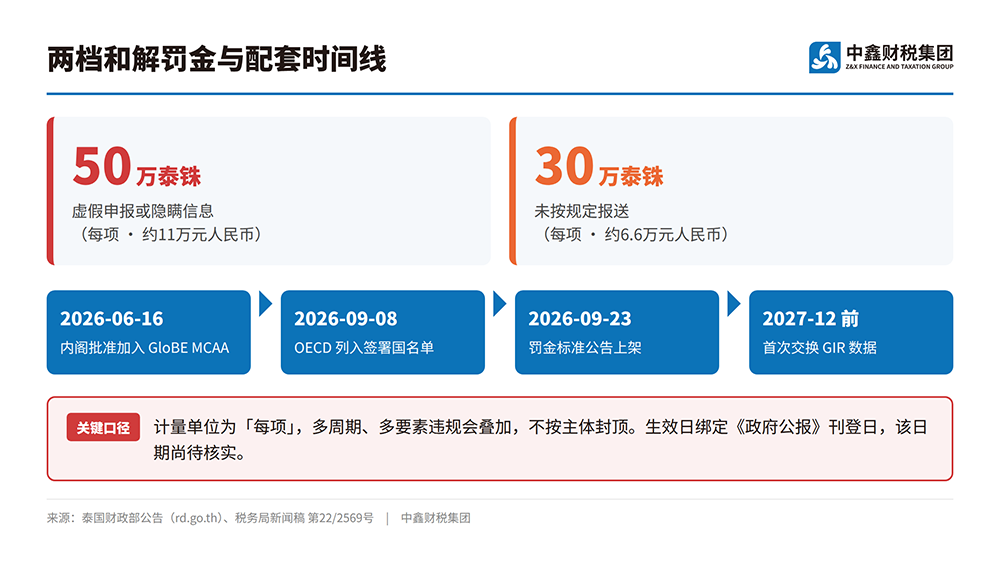
Item (1): Violating Sections 12, 17 or 18 of the decree, i.e. declaring false content or concealing facts, constitutes an offence under Section 28, with a fine of THB 500,000 per count (กระทง) (about RMB 110,000).
Item (2): Violating Section 20 of the decree, i.e. failing to fulfil the reporting obligation as required, constitutes an offence under Section 29, with a fine of THB 300,000 per count (about RMB 66,000).
Clause 2 sets the effective date: the notification takes effect from the date of its publication in the Royal Thai Government Gazette (ราชกิจจานุเบกษา).
2. The Word "Per Count" Determines the Scale of Risk
In the context of penalties, the Thai word กระทง means an "item", "instance" or "count" of an offence, close to "each time" or "each case" in Chinese tax law. This means fines are neither capped per year nor per entity, but accumulate according to the number of violations. If a group submits false or incomplete information across several reporting periods and several reporting elements, the fines can in theory add up.
This is where the real weight of the notification lies: the emergency decree itself has existed since B.E. 2566 (2023) and the obligations were clear, but until now there was no calculable answer to "what happens if you do not comply". Now the answer has been given, and it is measured "per count".
It should be stressed that the THB 500,000 / THB 300,000 figures are "settlement fine" standards, i.e. the amounts that apply when the party reaches a settlement with the tax authority and avoids criminal proceedings. They are not the same as the maximum penalties a court may impose. Their application must be judged case by case and is subject to the determination of the competent authority.
3. The Effective Date Is Not Yet Confirmed, but Preparation Should Not Wait
Clause 2 ties the effective date to the date of publication in the Government Gazette, and the notification itself does not state that date. As of the time of writing, we have not been able to verify the publication date, so the exact effective date remains to be confirmed.
For companies, however, "effective date to be confirmed" does not mean "we can wait". The reason is that this notification follows a timeline that is already running:
On 16 June 2026, the Thai Cabinet approved joining the GloBE MCAA (GloBE Information Return Multilateral Competent Authority Agreement);
On 8 September 2026, the OECD formally added Thailand to the list of signatories;
On 15 September 2026, the Thai Revenue Department confirmed this in press release ปชส.22/2569 and stated that the first exchange of GIR data will take place before December 2027.
In other words, the first real exchange of information will happen at the end of 2027, while the penalty standards were already in place in September 2026. The year or so in between is the window for companies to sort out their cross-border structures and reporting approach.
Key Takeaways
1. The Ministry of Finance notification sets two tiers of settlement fines: false declarations or concealed information, THB 500,000 per count (about RMB 110,000); failure to report as required, THB 300,000 per count (about RMB 66,000).
2. The unit of measurement is "per count" (กระทง): violations across multiple periods and multiple elements accumulate and are not capped per entity.
3. Signed on 2026-09-09 and posted on the Revenue Department website on 2026-09-23; the effective date is tied to the Government Gazette publication date, which is yet to be verified.
4. These are "settlement fine" standards, not the maximum penalties a court may impose; their application must be judged case by case and is subject to the determination of the competent authority.
5. Related timeline: on 2026-09-08 the OECD listed Thailand as a GloBE MCAA signatory, and the first exchange of GIR data will take place before December 2027.
Z&X Tip
Before the penalties take effect, we recommend that Chinese-invested groups in Thailand do three things: first, map out the local entity's role in the cross-border structure and its approach to related-party transactions, and confirm which entity bears the reporting obligation; second, check whether transfer pricing documentation and policies keep pace with the current structure; third, write the responsible reporting person and internal review steps into company policy, to avoid omissions caused by "nobody being in charge". Z&X's transfer pricing service (preparing transfer pricing documentation and setting compliance policies) and tax health check service, both part of our tax planning and risk control service line, address exactly these items.
Sources
• ประกาศกระทรวงการคลัง เรื่อง กำหนดหลักเกณฑ์การเปรียบเทียบตามมาตรา ๓๑ แห่งพระราชกำหนดการแลกเปลี่ยนข้อมูลเพื่อปฏิบัติตามความตกลงระหว่างประเทศเกี่ยวกับภาษีอากร พ.ศ. ๒๕๖๖ | Thai Ministry of Finance (กระทรวงการคลัง) | signed 2026-09-09, posted in the Revenue Department new-laws section 2026-09-23 | https://www.rd.go.th/fileadmin/user_upload/kormor/newlaw/mofcrsm31A.pdf
• Press release ปชส.22/2569 "ประเทศไทยลงนาม GloBE MCAA พร้อมเดินหน้าแลกเปลี่ยนข้อมูลภาษีกลุ่มบริษัทข้ามชาติ" | Thai Revenue Department (กรมสรรพากร) | 2026-09-15 | https://www.rd.go.th/59.html



 One on one exclusive financial and tax consultation